Preparing For Open Enrollment Season
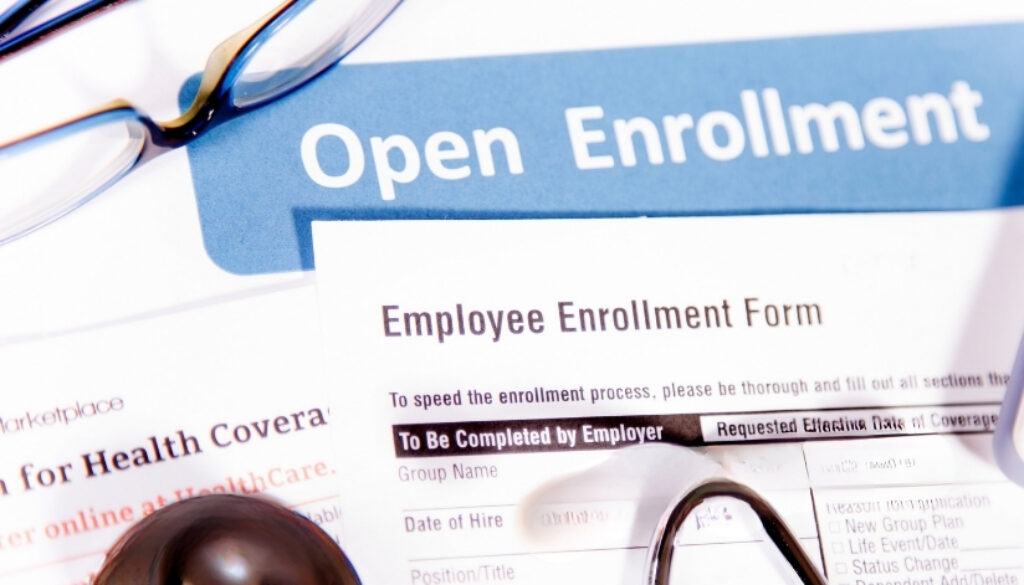
Open enrollment season gives employees an opportunity to review and update many of the workplace benefits that can affect their financial well-being throughout the coming year. While health insurance is often the primary focus, open enrollment can also be a good time to revisit retirement plan contributions, Health Savings Accounts (HSAs), Flexible Spending Accounts (FSAs), life insurance, disability coverage, and beneficiary designations.
Because employer-sponsored benefits often play an important role in an overall financial plan, reviewing your available options each year may help ensure your elections continue to reflect your healthcare needs, financial priorities, and changing life circumstances.
When Is Open Enrollment Season?
The timing of open enrollment depends on the type of health coverage you have.
For many employer-sponsored health plans, open enrollment takes place during the fall, often in October or November, for benefits that become effective January 1 of the following year. Benefit elections generally remain in effect until the next open enrollment period unless a qualifying life event occurs. Your employer’s Human Resources department can provide the specific dates, benefit options, and deadlines that apply to your workplace.
Other types of health coverage follow different enrollment periods:
- Health Insurance Marketplace (ACA) Plans: For 2027 coverage, the federal Health Insurance Marketplace open enrollment period generally runs from November 1, 2026, through December 15, 2026, for coverage beginning January 1, 2027. Some state-based marketplaces may have different deadlines.
- Medicare Annual Enrollment: Generally takes place October 15 through December 7, with coverage changes becoming effective January 1.
- Medicaid and CHIP: Individuals who qualify may enroll throughout the year rather than during a specific open enrollment period.
Review Your Health Insurance Coverage
Health insurance needs can change from year to year. During open enrollment, consider whether your current plan continues to meet your needs or if another available option may be a better fit.
Some factors to review include:
- Monthly premiums
- Deductibles
- Copays and coinsurance
- Provider networks
- Prescription drug coverage
- Expected healthcare needs for you and your family
Changes such as marriage, the birth of a child, or changes in your healthcare needs may influence which available plan options are most appropriate for your household.
Revisit Your Retirement Plan Contributions
Open enrollment can also be a good reminder to review your workplace retirement savings strategy.
Many employer-sponsored retirement plans allow employees to adjust their contribution percentage during open enrollment or throughout the year. Reviewing your current contribution rate may help determine whether it still aligns with your income, budget, and long-term retirement goals.
You may also wish to review:
- Whether you’re taking full advantage of any available employer matching contributions
- Recent changes in income or expenses
- Your overall retirement savings strategy
- Annual IRS contribution limits
Small adjustments made consistently over time may have a meaningful impact on long-term retirement savings.
Consider Your Health Savings Account (HSA)
If you are enrolled in a qualified High Deductible Health Plan (HDHP), you may be eligible to contribute to a Health Savings Account (HSA).
HSAs offer several potential advantages, including:
- Tax-deductible contributions (subject to IRS rules)
- Tax-deferred growth
- Tax-free withdrawals for qualified medical expenses
During open enrollment, you may wish to review your planned HSA contribution amount for the upcoming year and determine whether it continues to fit within your overall financial plan.
Review Flexible Spending Accounts (FSAs)
Employees who participate in a Flexible Spending Account may also want to revisit their contribution elections.
Depending on your employer’s plan, FSAs may be available for:
- Healthcare expenses
- Dependent care expenses
Because FSA rules and carryover provisions can vary by employer, reviewing your anticipated expenses before selecting a contribution amount may help you make the most of your available benefits.
Review Life And Disability Insurance
Many employers offer life insurance and disability insurance as part of their employee benefits package.
Open enrollment provides an opportunity to review whether your current coverage still reflects your financial responsibilities and family situation.
You may wish to consider:
- Changes in income
- Marriage or divorce
- The birth or adoption of a child
- A mortgage or other significant financial obligations
Reviewing these coverages periodically can help ensure they continue to support your broader financial plan.
Don’t Forget to Review Your Beneficiaries
Open enrollment is also a good reminder to review beneficiary designations on workplace retirement accounts, life insurance policies, and other employer-sponsored benefits.
Life events such as marriage, divorce, births, or deaths may make it appropriate to update beneficiary information. Keeping these designations current can help ensure your wishes are accurately reflected.
Think Beyond This Year’s Benefits
While open enrollment focuses on the upcoming plan year, it can also serve as an opportunity to step back and review your overall financial picture.
Questions you may wish to consider include:
- Are your retirement savings still aligned with your long-term goals?
- Has your emergency fund changed?
- Have your healthcare expenses increased?
- Have there been significant changes to your family or financial situation?
- Is your current financial plan still appropriate for your goals?
- Have your beneficiary designations been reviewed recently?
Looking at workplace benefits within the context of your broader financial plan may help you make more informed decisions.
How Advisors Management Group Can Help
Open enrollment decisions are just one part of a comprehensive financial plan.
At Advisors Management Group, we help clients understand how retirement planning, investment management, tax planning, healthcare costs, and other financial considerations work together. While your employer provides information about available benefit options, evaluating how those benefits fit into your overall financial goals may benefit from a broader planning perspective.
Whether you’re reviewing retirement savings, evaluating workplace benefits, planning for future healthcare expenses, or discussing your long-term financial goals, Advisors Management Group can help you understand how those decisions fit within your overall financial plan.
Contact Advisors Management Group
If you would like to review your financial plan or discuss how your workplace benefits fit into your long-term financial goals, contact Advisors Management Group.
Our team works with clients to develop personalized financial plans that consider retirement planning, investment management, cash flow, tax planning, healthcare expenses, education savings, business planning, and other long-term financial priorities.
Advisors Management Group, Inc. is a registered investment adviser whose principal office is located in Wisconsin. Opinions expressed are those of AMG and are subject to change, not guaranteed, and should not be considered recommendations to buy or sell any security. Past performance is no guarantee of future returns, and investing involves multiple risks, including, but not limited to, the risk of permanent losses. Please do not send orders via e-mail as they are not binding and cannot be acted upon. Please be advised it remains the responsibility of our clients to inform AMG of any changes in their investment objectives and/or financial situation. This commentary is limited to the dissemination of general information pertaining to AMG’s investment advisory/management services. Any subsequent, direct communication by AMG with a prospective client shall be conducted by a representative that is either registered or qualifies for an exemption or exclusion from registration in the state where the prospective client resides. A copy of our current written disclosure statement discussing our advisory services and fees continues to remain available for your review upon request.